
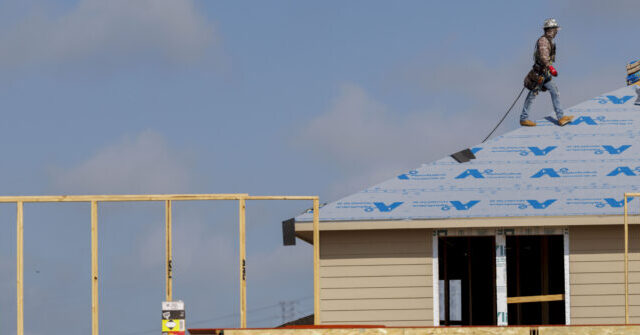
Housing Construction Grinds to Near-Standstill as American Dream Slips Further from Reach
American homebuilders just hit the brakes harder than they have in two years, with single-family housing starts plummeting to their lowest level since 2022—a stark warning sign that the Biden administration’s economic policies continue strangling the housing market.
The numbers tell a brutal story. Single-family construction collapsed 9.9 percent in July alone, dropping to an annual rate of just 808,000 units. That’s not a slowdown—that’s a freefall.
Year-over-year comparisons reveal the full scope of this crisis. Construction of single-family homes has cratered 15.7 percent compared to July of last year. Builders aren’t just pumping the brakes—they’re slamming them.
The total housing picture looks even worse. When you factor in apartments and condos, new construction plunged 12.4 percent to an annual pace of 1.239 million units. That marks a 13.5 percent nosedive from last year and represents the second-worst performance since the pandemic lockdowns of June 2020.
The Regulatory Stranglehold
Here’s what the mainstream media won’t tell you: this housing drought didn’t happen by accident. It’s the predictable result of excessive government intervention, suffocating regulations, and an administration more interested in pushing green energy mandates than helping families achieve homeownership.
Builders face an impossible gauntlet. Environmental red tape delays projects for months or years. Local zoning boards, dominated by not-in-my-backyard progressives, block sensible development. Federal mortgage policies under this administration have made financing more expensive and uncertain.
The result? Families priced out of the market. Young Americans stuck in their parents’ basements. The American Dream deferred—or cancelled entirely.
The Federal Reserve’s Role
The housing market remains in intensive care thanks to the Federal Reserve’s protracted campaign of elevated interest rates. While inflation required correction—inflation this administration created through reckless spending—the medicine has poisoned the patient.
Higher rates mean higher mortgage costs. Higher mortgage costs mean fewer buyers. Fewer buyers mean builders scale back construction. It’s Economics 101, yet policymakers seem determined to ignore basic cause and effect.
A Long Road from Rock Bottom
Despite the current malaise, construction levels remain above the dismal decade that followed the 2008 housing crash. That’s not exactly a high bar to clear.
Housing starts peaked in January 2006 at an annual pace of 2.273 million units before the bubble burst spectacularly. The market bottomed out in April 2009 at a catastrophic 478,000 units annually. The current rate sits uncomfortably between crisis and recovery—closer to stagnation.
The Permit Paradox
Here’s where things get interesting. While actual construction collapsed, permits for future single-family homes rose 2.5 percent to 894,000 units. They’re up 1.1 percent year-over-year. Total permits jumped 5.0 percent to 1.443 million units—surpassing expectations.
This disconnect reveals builder psychology. They’re cautiously optimistic about the future but terrified of the present. They’ll file permits—relatively cheap paperwork—but they won’t break ground until they see real demand and reasonable financing conditions.
That hesitation speaks volumes about business confidence under current leadership.
What Comes Next
The housing market won’t recover until we address fundamental problems. We need serious regulatory reform that streamlines the approval process without sacrificing legitimate safety standards. We need monetary policy that balances inflation control with economic growth. We need an administration that understands business doesn’t exist to fund progressive wish lists.
Most importantly, we need recognition that homeownership isn’t a privilege for the elite—it’s the cornerstone of middle-class wealth building and community stability.
The Bottom Line
These aren’t just statistics on a government spreadsheet. Behind every cancelled housing start is a family that won’t find their dream home. Behind every delayed project is a construction worker without a paycheck. Behind every discouraged builder is an entrepreneur who’s concluded the risk isn’t worth the regulatory headache.
The housing crisis won’t solve itself. It requires leadership willing to prioritize American families over bureaucratic empire-building. Until that changes, expect more of the same: declining construction, rising prices, and the continued hollowing out of the American middle class.
The data doesn’t lie. The housing market is sending a distress signal. The only question is whether anyone in Washington is listening—or whether they’re too busy congratulating themselves on their latest spending spree to notice the damage they’ve done.


